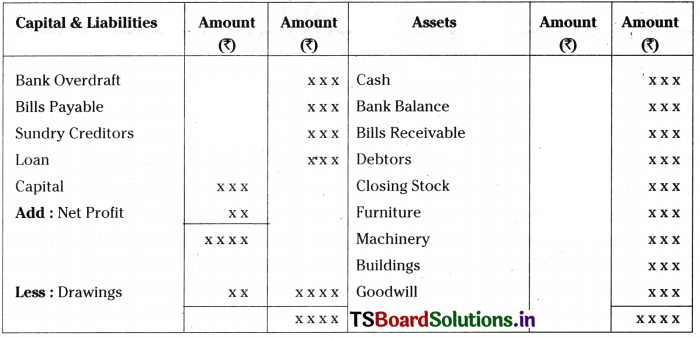
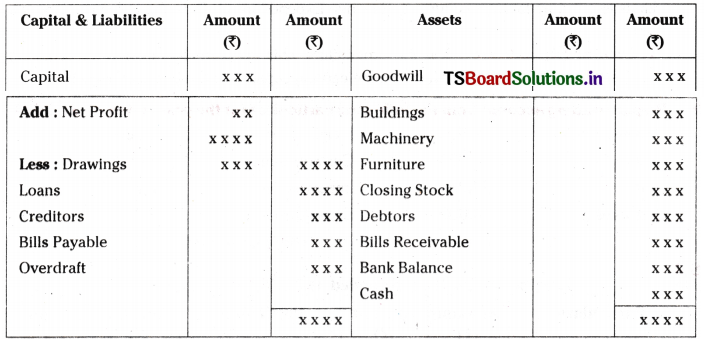
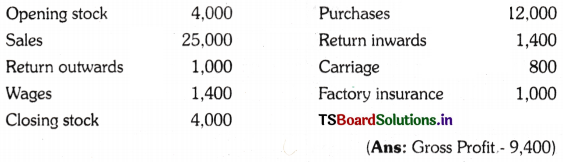
Regular practice with AP Inter 1st Year Accounts Study Material Chapter 12 Final Accounts with Adjustments Questions and Answers helps students stay prepared for examinations.
AP Inter 1st Year Accountancy 12th Lesson Final Accounts with Adjustments Questions and Answers
I. Fill in the blanks
Question 1.
Closing stock given in the Trial Balance should be recorded only on the ……. of Balance sheet.
Answer:
Assets side
Question 2.
Outstanding salaries given in the Trial Balance should be recorded on the …… of the Balance Sheet.
Answer:
Liabilities side
Question 3.
The decline in the value of fixed Asset is called ……..
Answer:
Depreciation
Question 4.
Bad Debts given in the Trial Balance should be recorded on the …… of the Profit and Loss Account.
Answer:
Debit side
Question 5.
Bad Debts given in the adjustments should be recorded on the Debit side of the Profit and Loss Account and immediately deducted from the …….. on the Asset side
Answer:
Debtors
Question 6.
Interest on Capital given in the Trial Balance should be recorded on the Debit side of the ……….
Answer:
Profit & Loss account
Question 7.
Interest on drawings given in the Trial Balance should be recorded on the Credit side of the …….
Answer:
Profit & Loss account
II. Very Short Answer Type Questions
Question 1.
What is the meaning of adjustment?
Answer:
To find out net profit and true financial position, all expenses relating to current year, whether actually paid or not, all incomes received or yet to be received should be taken into account. Some of the incomes and expenses relating to next year, but received and paid in the current year should not be included in the accounts of current year. The amount to be adjusted to the concerned items is called adjustment. E.g : Outstanding salaries, prepaid insurance, etc.
Question 2.
Explain the importance of adjustment.
Answer:
- Expenses or incomes relating to the accounting period can be known accurately.
- Profit or loss can be ascertained accurately.
- Real value of assets and liabilities can be ascertained easily.

Question 3.
Give the meaning of bad debts.
Answer:
The debts which are not collected or irrecoverable are known as bad debts.
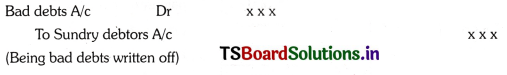
Adjustment entry :
III. Short Answer Type Questions
Question 1.
Write the following
a) Interest on Capital
Answer:
The amount of interest payable on owner’s capital by the business organisation is called interest on capital.
Adjustment entry :
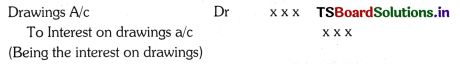
Accounting treatment in final accounts :
When interest on capital is given as an adjustment.
1. Debit in P & L A/c and
2. It should be added to the capital in balance sheet.
Note : When it is given in trial balance, debit it in P & L A/c only.
b) Interest on Drawings.
Answer:
Drawings mean the amount of cash or goods taken by the trader for personal use.
The amount of interest payable by the owner to the business is called interest on drawings.
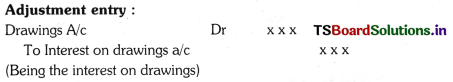
Accounting treatment in final accounts :
When interest on drawings given as adjustment.
1. It is to be recorded on credit side of P & L A/c and
2. Deduct the amount from capital in Balance sheet.
Note : When interest on drawings is given in trial balance, it should be shown on credit side in Profit & Loss A/c.
IV. Essay Questions
Question 1.
Describe the various types of adjustments with examples.
Answer:
Types of Adjustments :
1. Adjustments relating to closing stock : Closing stock means, the stock of goods unsold at the end of accounting year.
Adjustment entry :
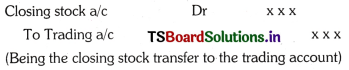
Accounting treatment in final accounts :
1) Show on the credit side of trading A/c
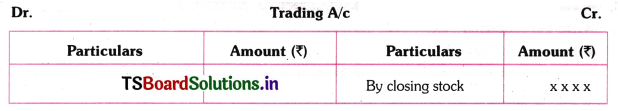
2) Show on the assets side of balance sheet.
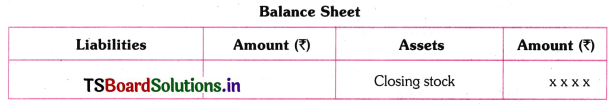
Note : If closing stock is given in Trial Balance, show it on the Assets side of Balance sheet.
2. Adjustments relating to expenses :
a) Outstanding expenses : Expenses relating to the current accounting year but not yet paid and are to be paid in the next year e.g : Salary for the month of December is due but not paid.
Adjustment entry :
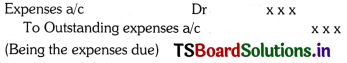
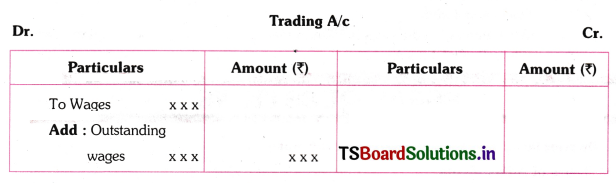
Accounting treatment in final accounts :
1) Add either in trading A/c or in profit & loss A/c to the concerned expenditure item.
Problems
Question 1.
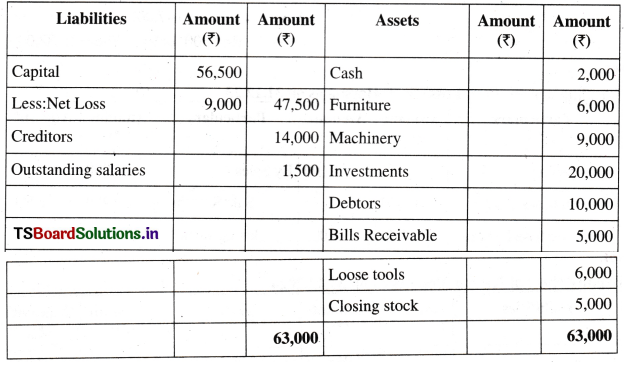
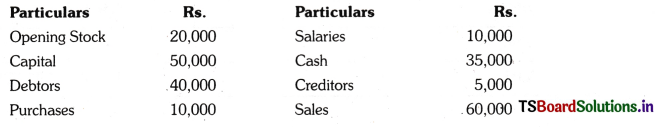
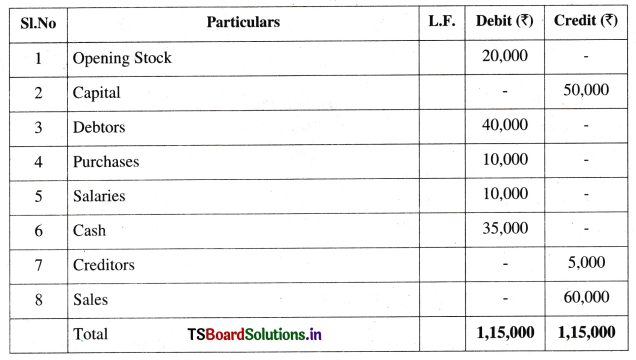
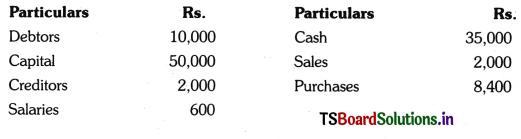
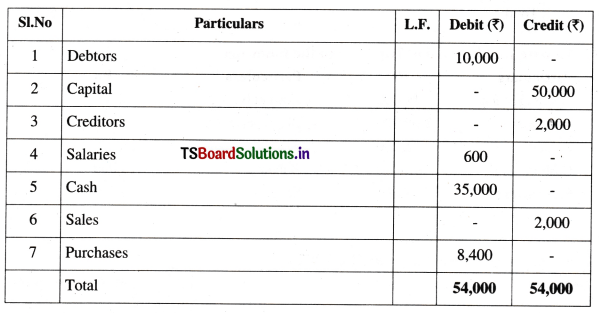
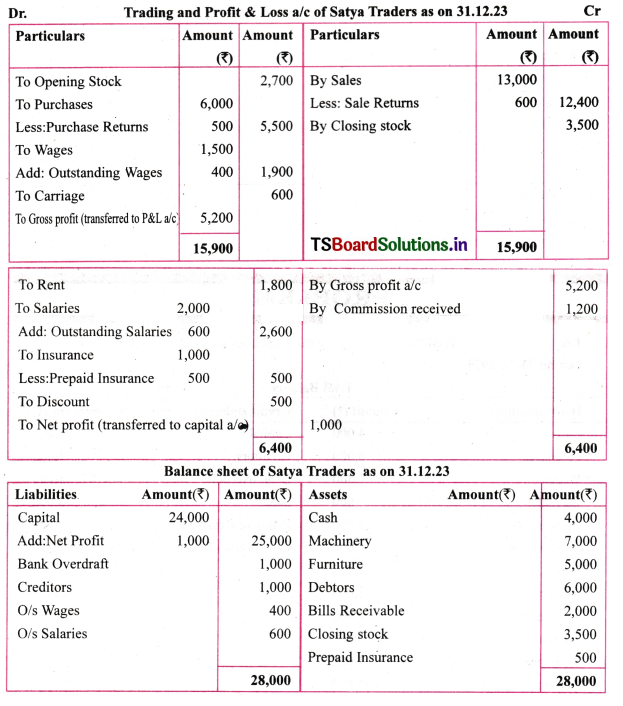
From the following Trial Balance, prepare the final accounts of Sathya Traders for the year ending 31-12-2023.
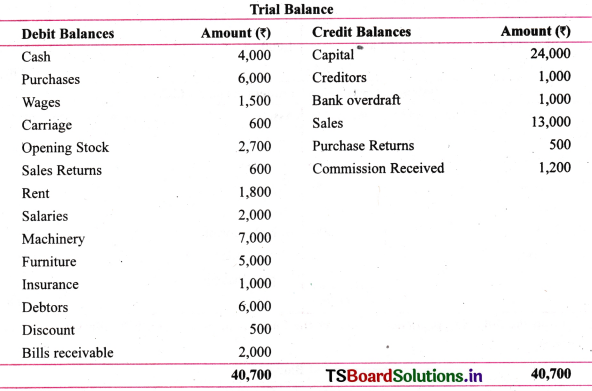
Adjustments:
1) Closing Stock ₹ 3,500
2) Outstanding Wages ₹ 400
3) Outstanding Salaries ₹ 600
4) Prepaid Insurance ₹ 500
Answer:
Question 2.
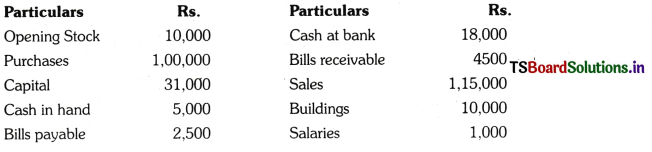
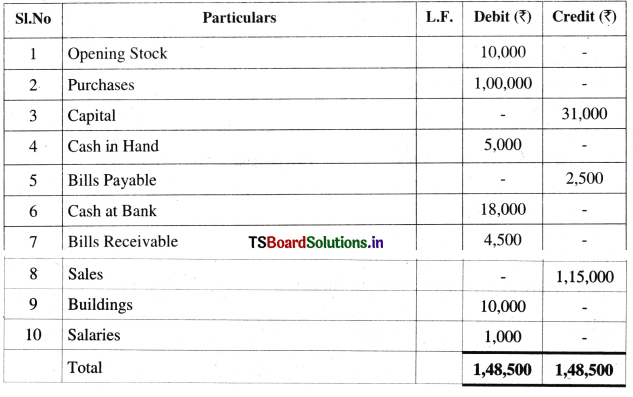
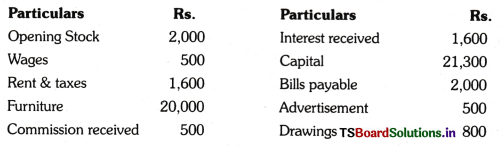
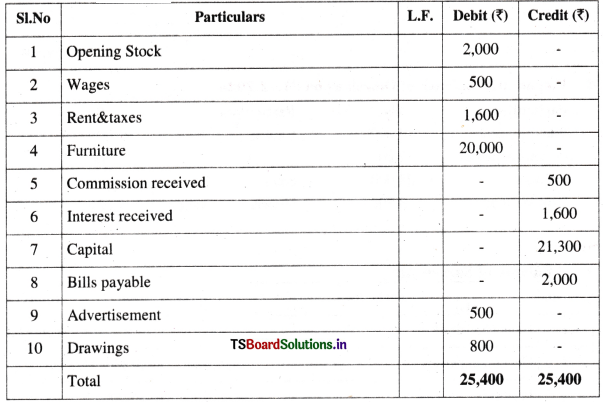
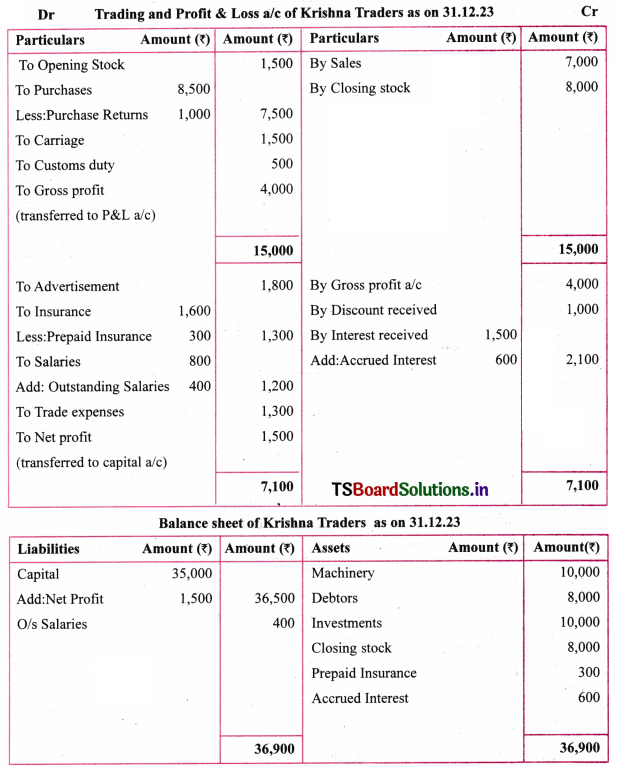
From the following particulars, prepare the final accounts of Krishna Traders as on 31-12-2023.
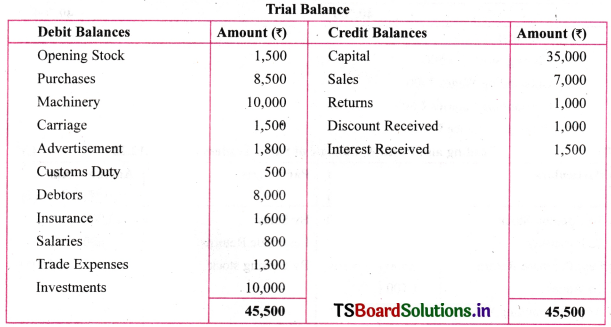
Adjustments:
1) Closing Stock ₹ 8,000
2) Prepaid Insurance ₹ 300
3) Outstanding Salaries ₹ 400
4) Accrued Interest ₹ 600
[Ans: Gross Profit: ₹ 4,000; Net Profit: ₹ 1,500, B/S; ₹ 36,900]
Answer:
Question 3.
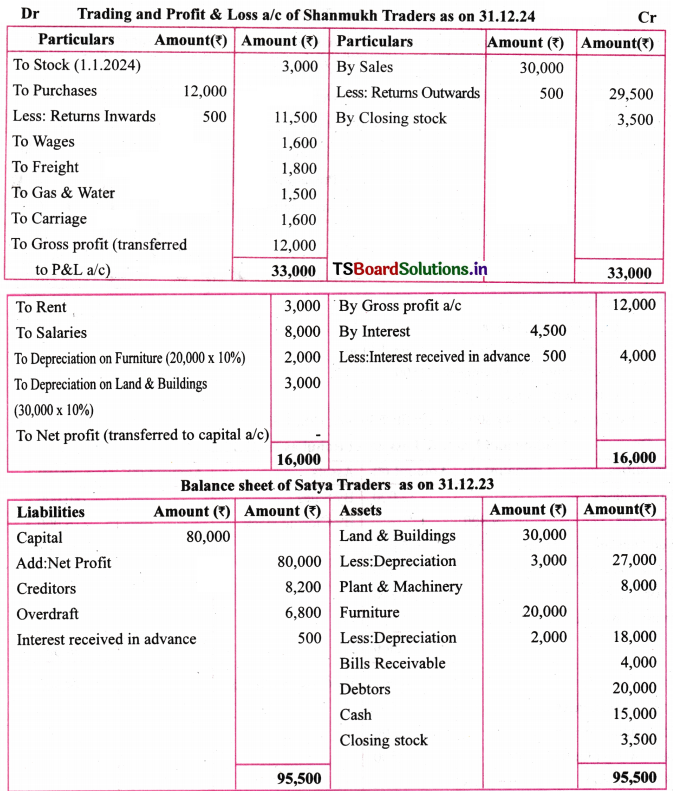
From the following particulars, prepare the final accounts of Shanmukh Traders for the year ending 31-12-2024.
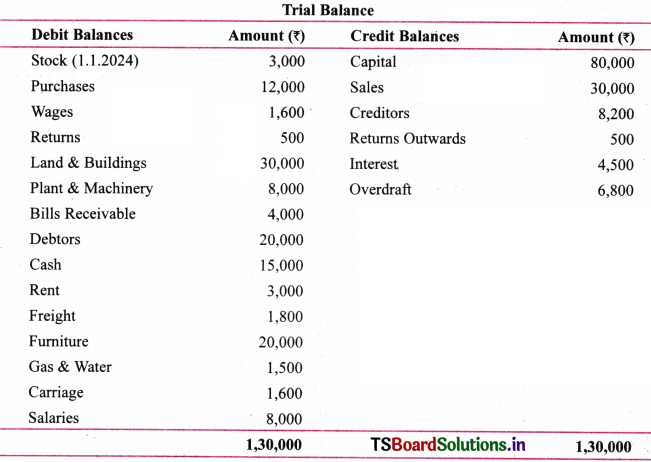
Adjustments:
1) Closing Stock ₹ 3,500
2) Provide depreciation @ 10% on Furniture
3) Provide depreciation @ 10% on Land & Buildings
4) Interest received in advance ₹ 500
[Ans: Gross Profit: ₹ 12,000; Net Profit: Nil, B/S; ₹ 95,500]
Answer:
Question 4.
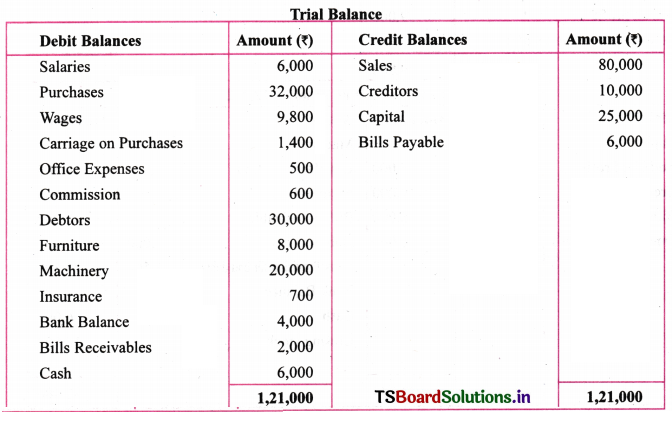
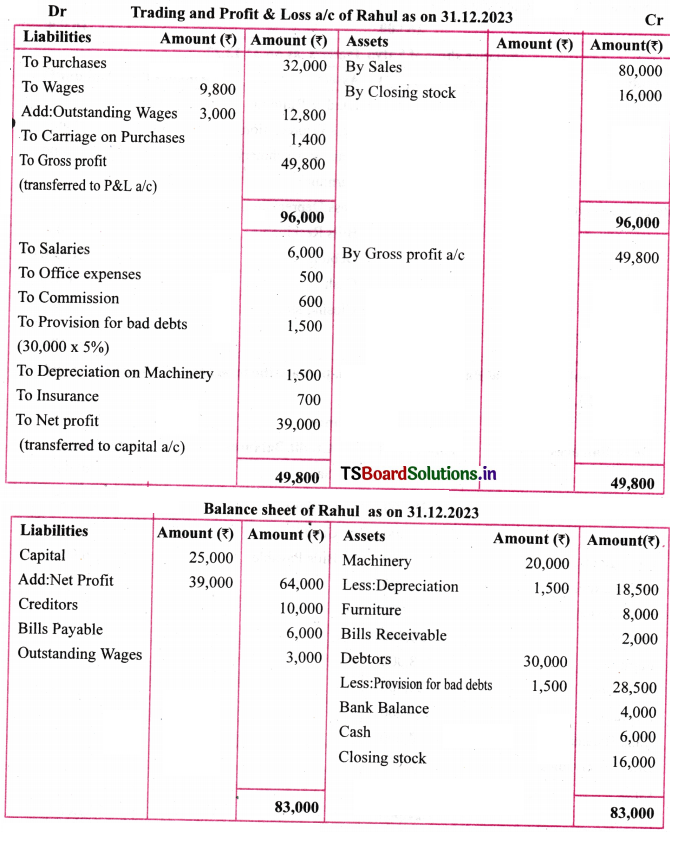
From the following Trial Balance of Mr. Rahul, prepare the final accounts for the year ended 31-12-2023.
Adjustments:
1) Closing Stock ₹ 16,000
2) Create 5% reserve for bad debts on debtors
3) Depreciation on Machinery ₹ 1500
4) Outstanding wages ₹ 3,000
[Ans: Gross Profit: ₹ 49,800; Net Profit: ₹ 39,000, B/S; ₹ 83,000]
Answer:
Question 5.
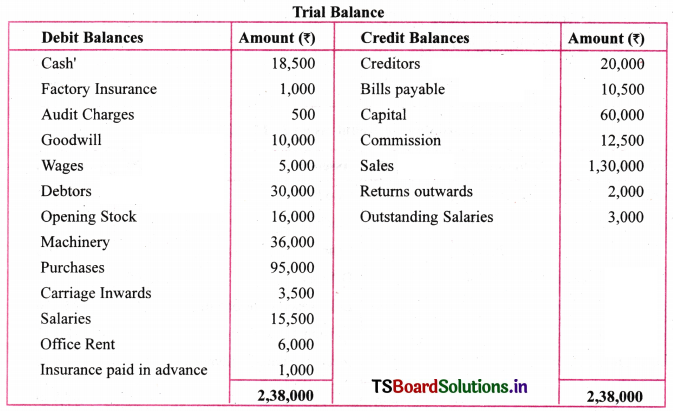
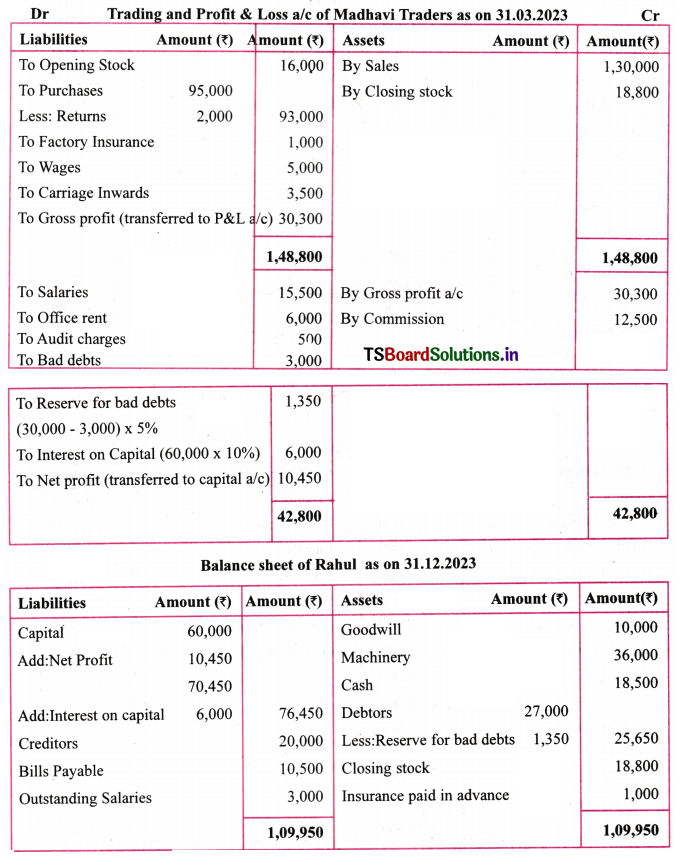
From the following particulars of Madhavi Traders, prepare the final accounts for the year ended 31-03-2023.
Adjustments:
1) Closing Stock Rs. 18,800
2) Interest on Capital @ 10%
3) Write off Rs. 3,000 as bad debts and provide 5% reserve for doubtful debts. [Ans: Gross Profit: Rs. 30,300; Net Profit: Rs. 10,450, B/S; Rs. 1,09,950]
Answer:
Question 6.
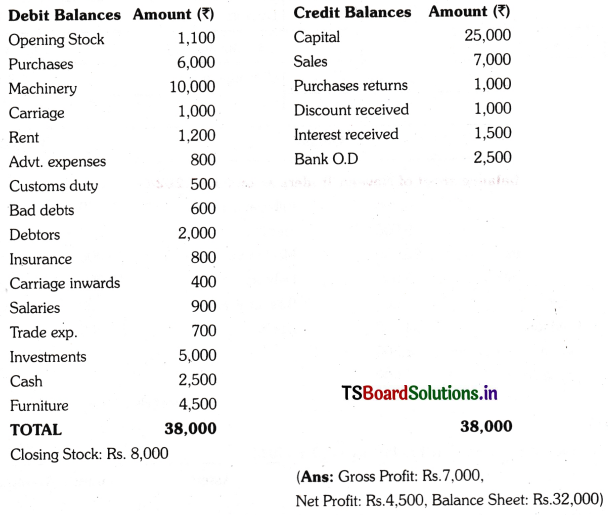
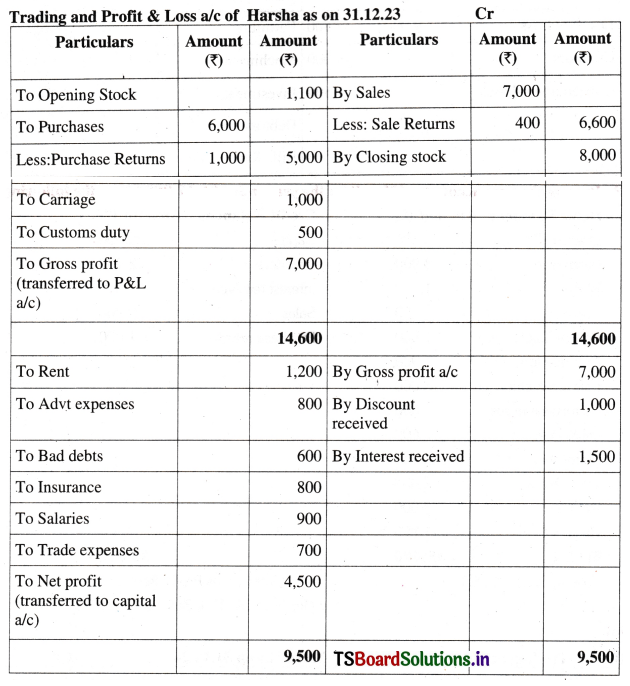
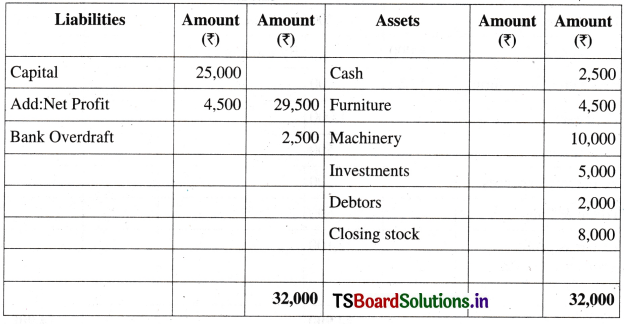
Prepare the final accounts of Harsha Traders for the year ending 31-03-2023.
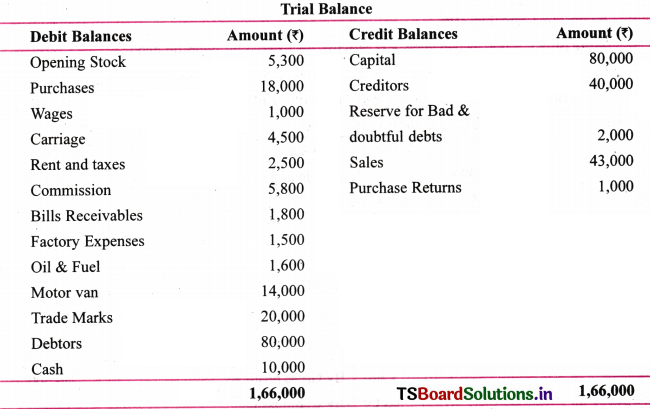
Adjustments:
1) Closing Stock Rs. 8,000
2) Depreciation on Motor Van 10%
3) Create Reserve for Bad & Doubtful Debts 5%
[Ans: Gross Profit: Rs. 20,100; Net Profit : Rs. 8,400, B/S; Rs. 1,28,400]
Answer:
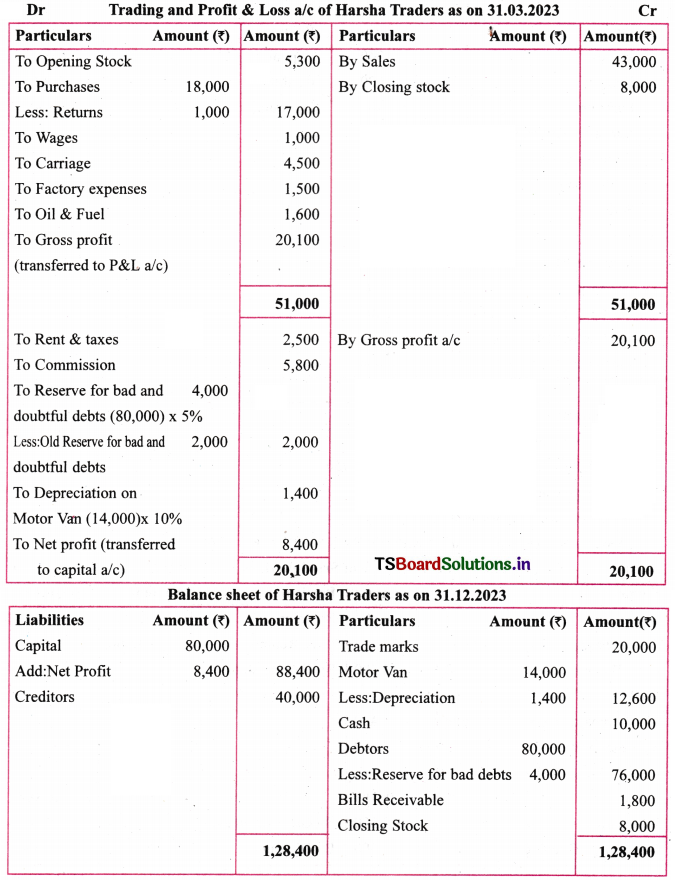
Question 7.
Prepare the final accounts of Sri Mahesh for the year ending 31-12-2023.
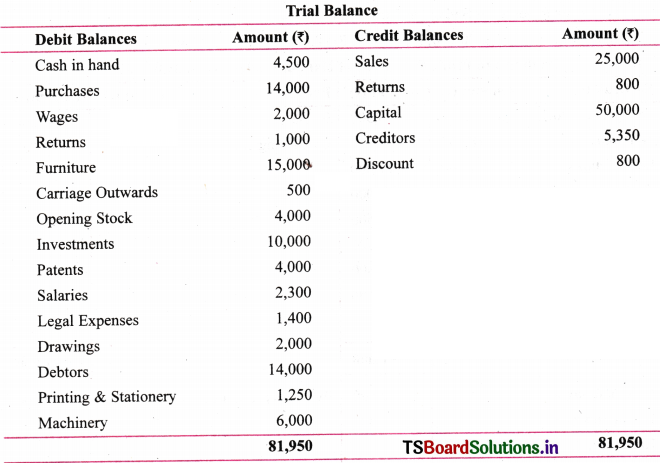
Adjustments:
1) Closing Stock Rs. 4,100
2) Outstanding Printing & Stationery Rs. 750
3) Depreciation on Machinery @ 10%
4) Prepaid Wages Rs. 600
[Ans: Gross Profit: Rs. 9,500; Net Profit: Rs. 3,500, B/S; Rs. 57,600]
Answer:
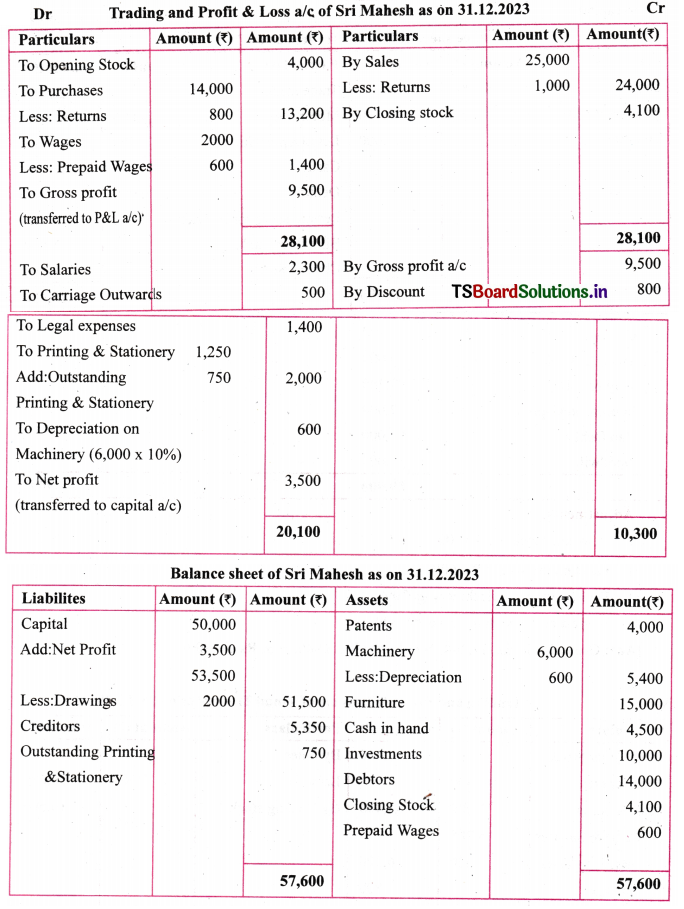
Question 8.
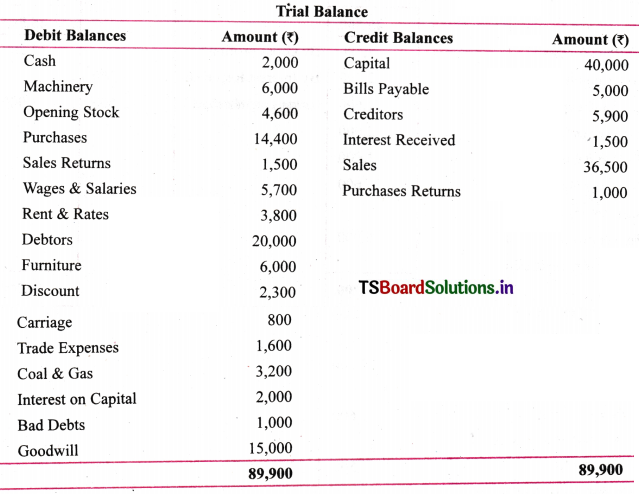
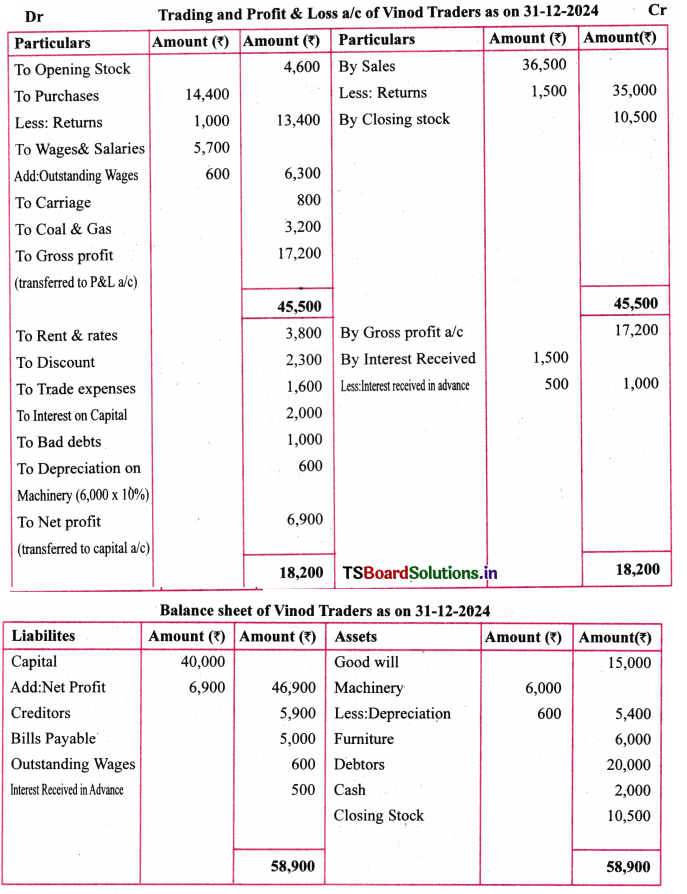
From the following Trial Balance of Vinod Traders, prepare final accounts for the year ended 31-12-2024.
Adjustments :
1) Closing Stock Rs. 10,500
2) Outstanding wages Rs. 600
3) Depreciation on Machinery @ 10%
4) Interest received in advance Rs. 500
[Ans: Gross Profit: Rs. 17,200; Net Profit: Rs. 6,900, B/S; Rs. 58,900]
Answer:
Question 9.
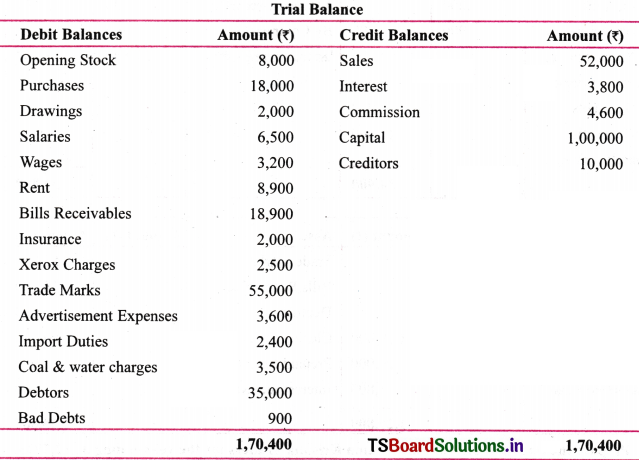
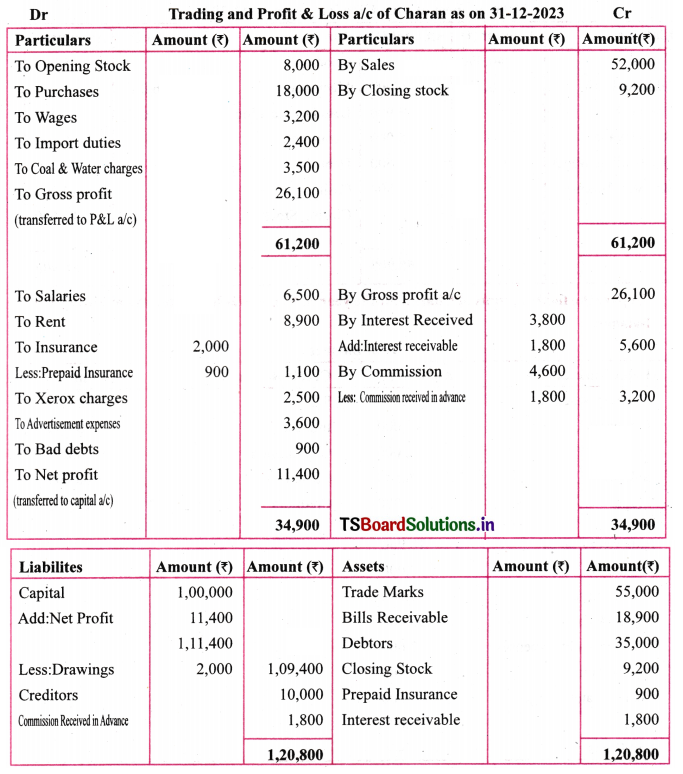
Prepare the final accounts of Charan for the year ending 31-12-2023, from the following Trail Balance.
Adjustments:
1) Closing Stock Value Rs. 9,200
2) Commission received in advance Rs. 1,400
3) Interest Receivable Rs. 1,800
4) Prepaid Insurance Rs. 900
[Ans: Gross Profit: Rs. 26,100; Net Profit: Rs. 11,400, B/S; Rs. 1,20,800]
Answer:
Question 10.
Prepare the final accounts of Shiva Rama Krishna Traders for the year ending 31.12.2023.
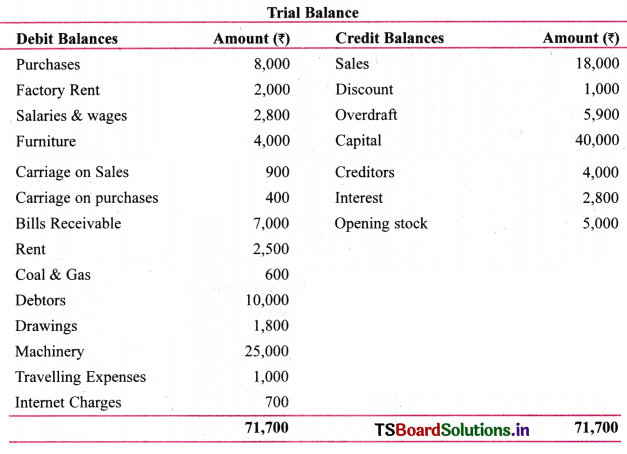
Adjustments:
Adjustments
1) Closing Stock Value Rs. 4,000
2) Outstanding Rent Rs. 600
3) Prepaid Salaries & Wages Rs. 500
4) Provide depreciation on Machinery @ 10%
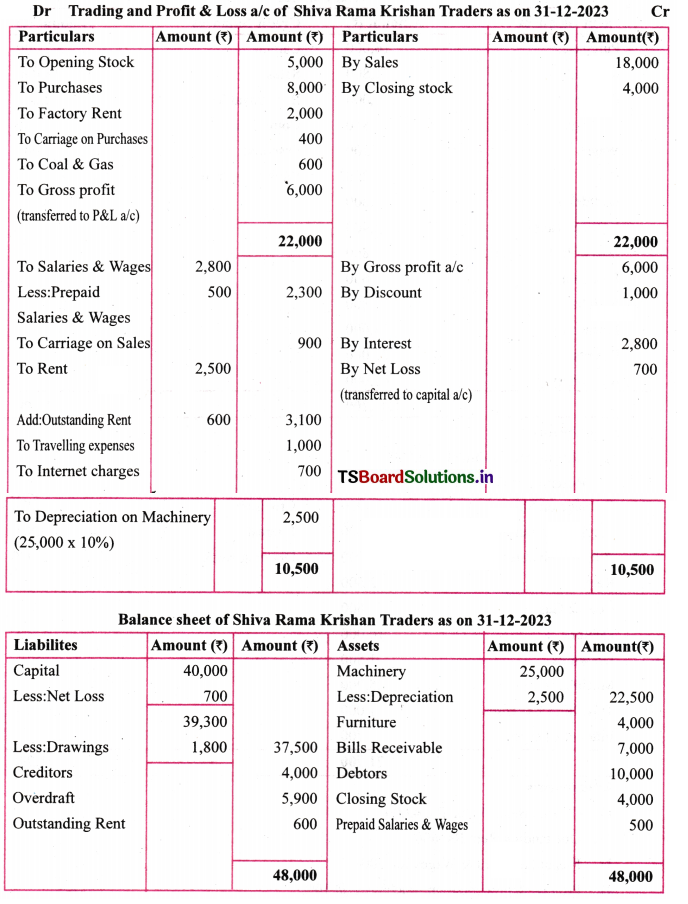
[Ans: Gross Profit: Rs. 6,000; Net Loss : Rs. 700, B/S; Rs. 48,000]
Answer:
Question 11.
Prepare the final accounts of Ramesh Traders for the year ended 31-12-2023.
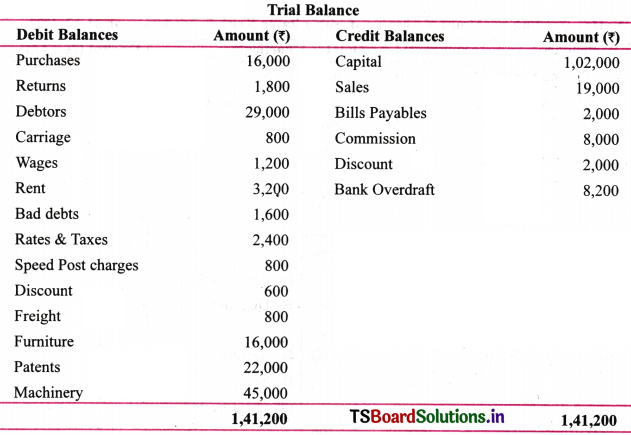
Adjustments
1) Closing Stock Value Rs. 8,000
2) Reserve for Bad Debts @ 5%
3) Depreciation on Patents @ 10%
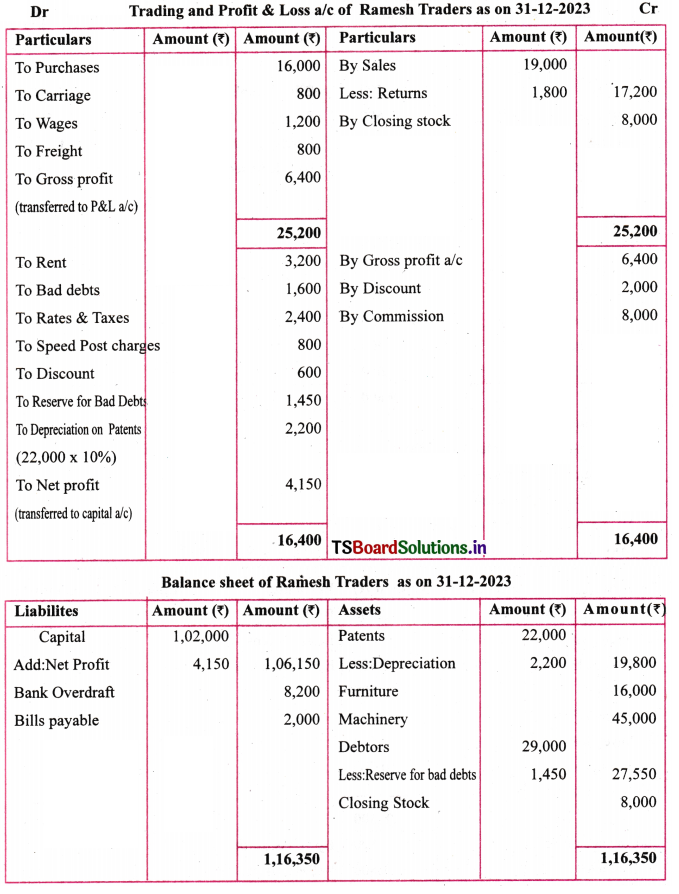
[Ans: Gross Profit: Rs. 6,400; Net Profit: Rs. 4,150, B/S; Rs. 1,16,350]
Answer:
Question 12.
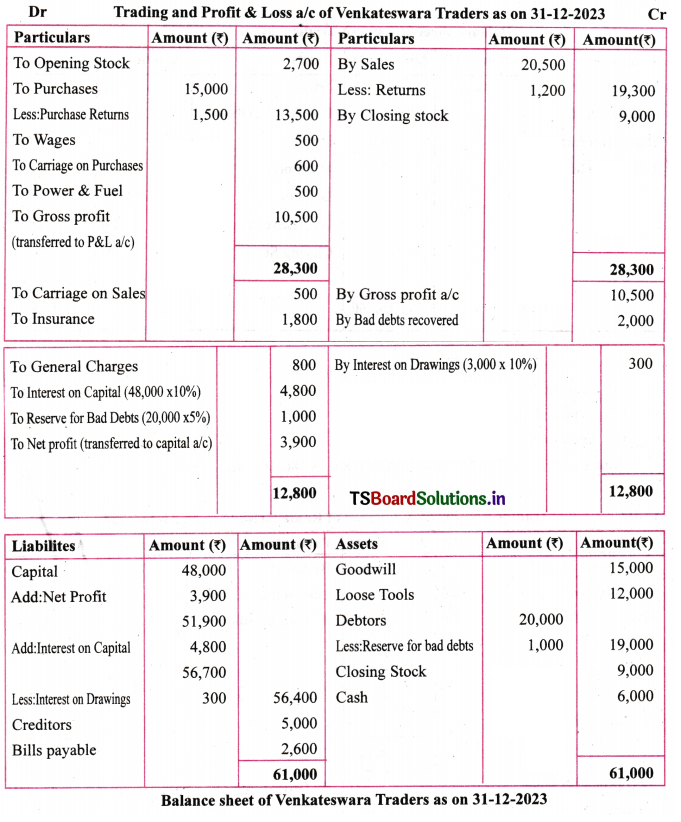
Prepare the final accounts of Venkateswara Traders for the year ended 31-12-2022.
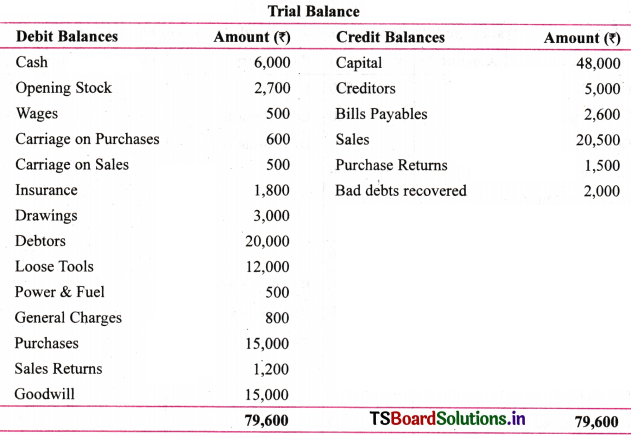
Adjustments
1) Closing Stock Value Rs. 9,000
2) Calculate Interest on capital @ 10%
3) Interest on Drawings @ 10%
4) Provide reserve for Bad debts@5%
[Ans: Gross Profit: Rs. 10,500; Net Profit: Rs. 3,900, B/S; Rs. 61,000]
Answer:
Question 13.
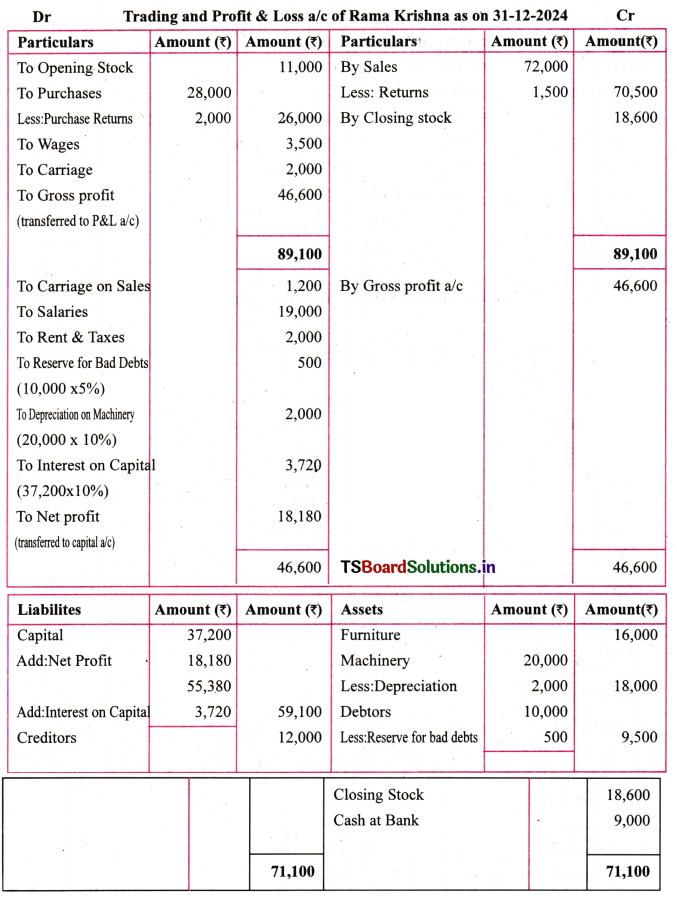
From the following Trial Balance of Mr. Rama Krishna, prepare final accounts for the year ended 31-12-2024.
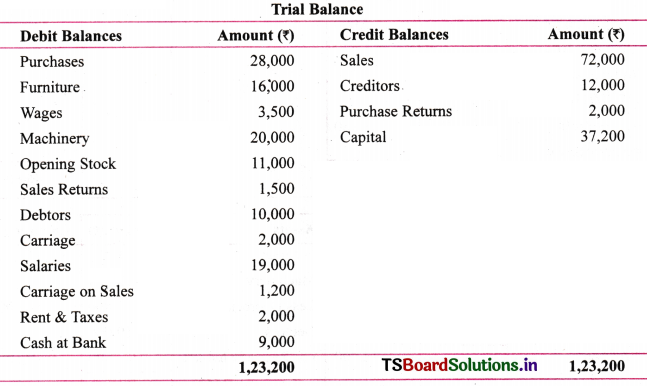
Adjustments
1) Closing Stock Value Rs. 18,600
2) Provide Reserve on Debtors @5%
3) Depreciation on Machinery @10%
4) Interest on Capital @10%
[Ans: Gross Profit: Rs. 46,600; Net Profit: Rs. 18,180, B/S; Rs. 71,100]
Answer:
Question 14.
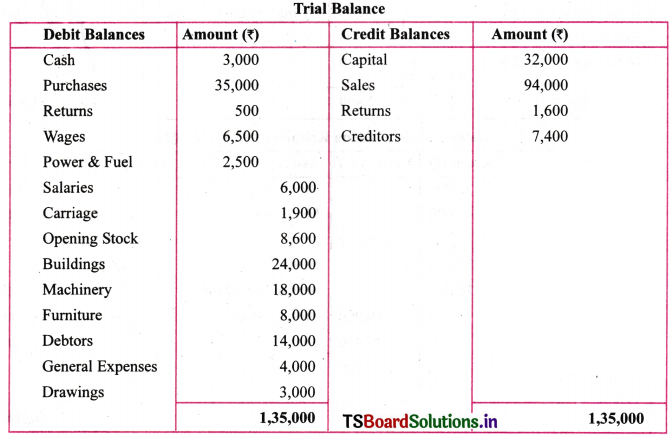
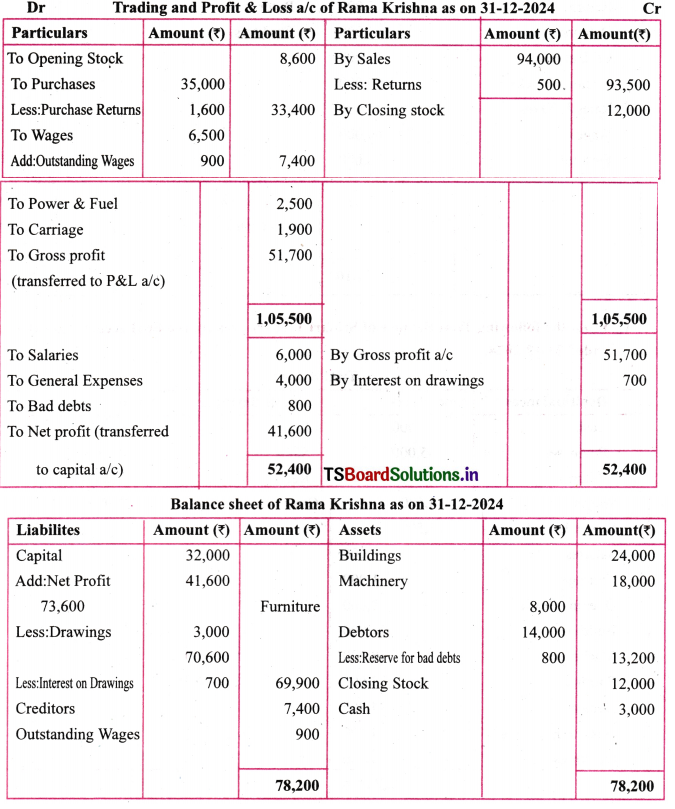
From the following Trial Balance of Srihari Traders prepare the final accounts for the year ended 31-12-2024.
Adjustments
1) Closing Stock Rs. 12,000
2) Outstanding wages Rs. 900
3) Bad debts Rs. 800
4) Interest on Drawings Rs. 700
[Ans: Gross Profit: Rs. 51,700; Net Profit: Rs. 41,600, B/S; Rs. 78,200]
Answer:
Question 15.
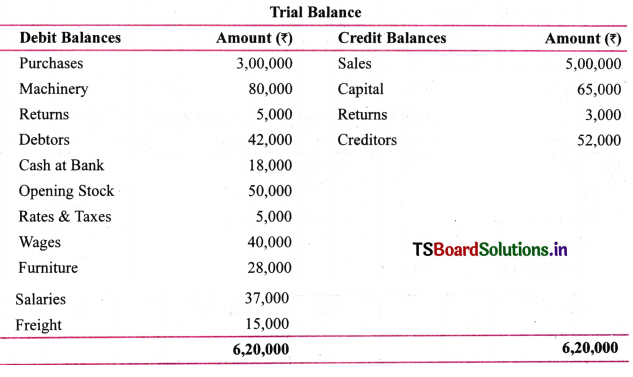
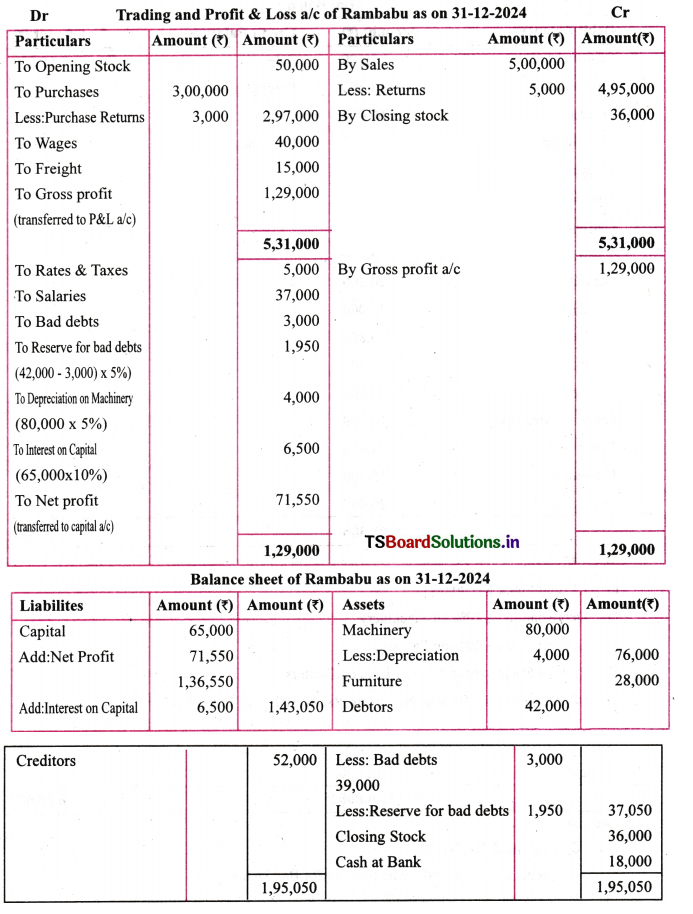
Prepare the final accounts of Rambabu for the year ending 31-12-2024 from the following Trial Balance.
Adjustments
1) Closing Stock Rs. 36,000
2) Bad debts Rs. 3,000 and create Reserve for Bad Debts @ 5%
3) Depreciation on Machinery @ 5%
4) Interest on Capital @ 10%
[Ans: Gross Profit: Rs. 1,29,000; Net Profit: Rs. 71,550, B/S; Rs. 1,95,050]
Answer:
Question 16.
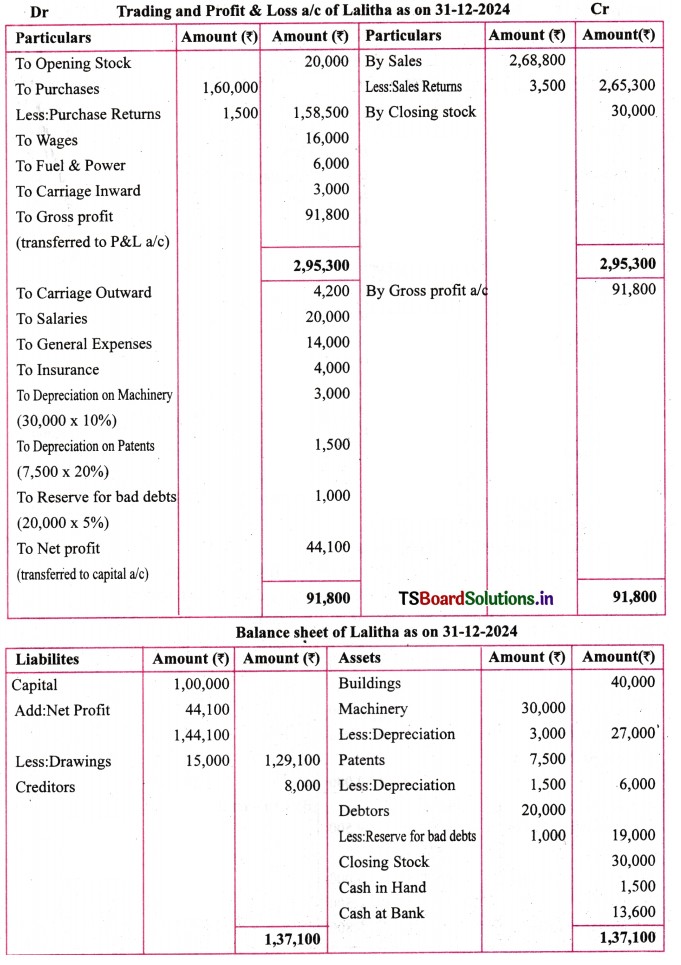
From the following Trial Balance and additional information of Lalitha, Prepare the final accounts for the year ending 31-12-2024
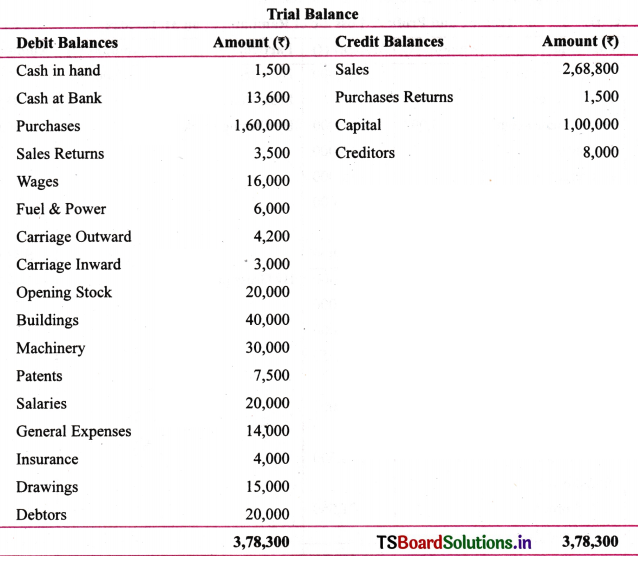
Adjustments
1) Closing Stock Rs. 30,000
2) Depreciation @ 10% on Machinery
3)Depreciation @ 20% on Patents
4) Provide 5% provision for bad debts on Debtors.
[Ans: Gross Profit: Rs. 91,800; Net Profit: Rs. 44,100, B/S; Rs. 1,37,100]
Answer:
Question 17.
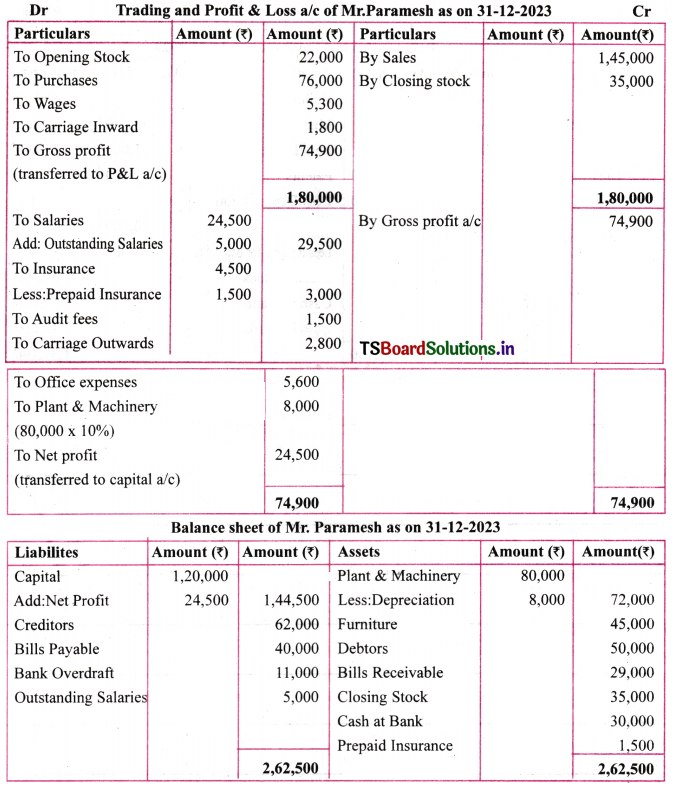
From the following Trial Balance of Mr. Paramesh, prepare the Trading a/c, P & L a/c and Balance sheet for the year ended 31-12-2023.
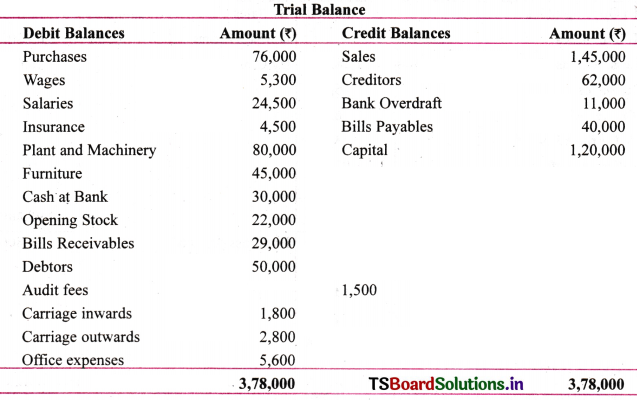
Adjustments
1) Closing Stock Rs. 35,000
2) Outstanding Salaries Rs.5,000
3) Prepaid Insurance 1,500
4) Depreciation on Plant & Machinery @ 10%
[Ans: Gross Profit: Rs. 74,900; Net Profit: Rs. 24,500, B/S; Rs. 2,62,500]
Answer: