Reviewing AP Inter 2nd Year Accounts Study Material Chapter 2 Accounting for Not-For-Profit Organisations Questions and Answers can help students prepare confidently for exams.
AP Inter 2nd Year Accountancy 2nd Lesson Accounting for Not-For-Profit Organisations Questions and Answers
I. Fill in the blanks
Question 1.
The main objective of a non-trading organisation is to provide ____.
Answer:
Service
Question 2.
____ Account resembles the Cash Book of a trading concern.
Answer:
Receipts & Payments
Question 3.
____ Account resembles the Profit & Loss Account of a trading concern.
Answer:
Income & Expenditure
Question 4.
The excess of income over expenditure is called ____.
Answer:
Surplus
Question 5.
The excess of expenditure over income is called ___.
Answer:
Deficit
II. Very Short Answer Questions
Question 1.
What is a Non-Trading Concern?
Answer:
A Non-Trading Concern is an organisation established to provide services to society or its members rather than to make a profit. Examples include charitable trusts, sports clubs, libraries, and educational institutions.
Question 2.
What is Capital Expenditure? Explain with an example.
Answer:
Capital Expenditure is the money spent on acquiring long-term assets that are useful for more than one accounting year. Examples include the purchase of land, buildings, furniture, or motor vehicles.
Question 3.
What is a Capital Receipt? Give an example.
Answer:
A Capital Receipt is an amount received that increases the capital of the organisation and does not occur regularly. Examples include capital fund, bank loans, and proceeds from the sale of assets.
Question 4.
Describe Revenue Receipts with one example.
Answer:
Revenue Receipts are amounts received during the normal activities of the organisation and are received regularly. An example is subscriptions collected from members.

Question 5.
Write about Revenue Expenditure with one example.
Answer:
Revenue Expenditure refers to the expenses incurred for the routine operations of the organisation. Examples include salaries, rent, wages, and insurance expenses.
Question 6.
Write a short note on Legacies.
Answer:
- Legacies are amounts received by an organisation through the will of a deceased person.
- They are non-recurring in nature and are treated as capital receipts, which are shown on the liabilities side of the Balance Sheet.
Question 7.
What is a Subscription?
Answer:
- A Subscription is the amount paid regularly by the members of a non-trading organisation.
- It is one of the major sources of income and is recorded on the credit side of the Income & Expenditure Account.
Question 8.
What are Donations? Mention the types of donations.
Answer:
Donations are amounts received by non-trading organisations from the general public.
Types of Donations:
- General Donation – Considered as income of the organisation.
- Specific Donation – Treated as a liability and utilised only for the purpose for which it is received.
III. Short Answer Questions
Question 1.
Write any four differences between Trading and Non-Trading Concerns.
Answer:
| Basis | Trading Organisations | Non-Trading Organisations |
| Objective | Established to earn profits | Established to provide services |
| Sources of Funds | Capital invested by owners | Capital fund, donations, and subscriptions |
| Financial Statements | Trading A/c, Profit & Loss A/c, and Balance Sheet | Receipts & Payments A/c, Income & Expenditure A/c, and Balance Sheet. |
| Result | Shows Net Profit or Net Loss | Shows Surplus or Deficit |
Question 2.
Write any four differences between Receipts & Payments A/c and Income & Expenditure A/c.
Answer:
| Basis | Receipts & Payments A/c | Income & Expenditure A/c |
| Nature | It is a Real Account | It is a Nominal Account |
| Items Recorded | Records all receipts and payments | Records only revenue incomes and revenue expenses |
| Basis | Prepared on a cash basis | Prepared on an accrusal basis |
| Closing Result | Displays the closing cash and bank balance | Displays the surplus or deficit for the year |
Question 3.
Explain the term Donations and classify them with examples.
Answer:
Donations are amounts received from the public to support the activities and objectives of a non-trading organisation.
Classification:
- General Donation
- Received for meeting the general expenses of the organisation.
- Credited to the Income & Expenditure Account. Example: Donation received from the public for the regular activities of a club.
- Specific Donation
- Received for a particular or specified purpose,
- Shown on the liabilities side of the Balance Sheet. Example: Donation collected for a Building Fund.
Question 4.
How do you prepare an Income & Expenditure Account from a Receipts & Payments Account?
Answer:
Steps involved in preparing the Income & Expenditure Account:
- Ignore the opening and closing balances of cash and bank.
- Take only revenue receipts and revenue expenses, excluding all capital items.
- Include only the incomes and expenses that relate to the current accounting year.
- Make necessary adjustments for outstanding and prepaid expenses.
- Adjust non-cash items such as depreciation and profit or loss on the sale of fixed assets.
- The final balance indicates either the surplus or deficit for the accounting year.
IV. Long Answer Questions
Question 1.
Distinguish between Trading and Non-Trading Concerns.
Answer:
| Basis | Trading Organisations | Non-Trading Organisations |
| Objective | Formed to earn profits | Formed to provide services |
| Sources of Funds | Capital invested by the owners | Capital fund, donations, and subscriptions |
| Financial Statements | Trading A/c, Profit & Loss A/c, and Balance Sheet | Receipts & Payments A/c, Income & Expenditure A/c, and Balance Sheet |
| Result | Shows Net Profit or Net Loss | Shows Surplus or Deficit |
| Main Activity | Engaged in buying and selling of goods | Engaged in providing services only |
| Accounting Focus | Gives importance to profit earning | Gives importance to rendering services to members or the public |
| Owners | Owned by individuals or partners | Managed by a committee or trustees; there are no owners |
| Examples | Business firms | Clubs, schools, hospitals, and charitable institutions |
Exercises
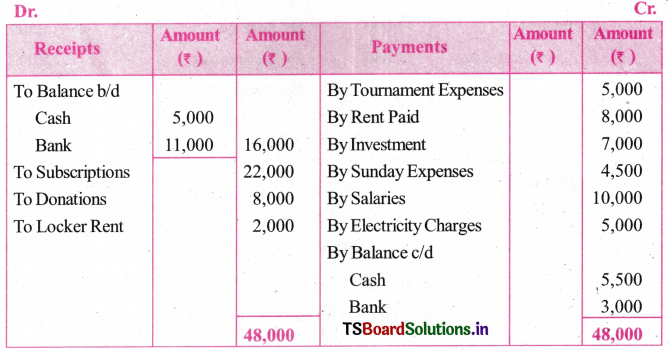
Question 1.
Prepare Receipts & Payments Account from the following particulars
Opening Cash in Hand – 5,000
Subscriptions – 22,000
Tournament Expense – 5,000
Investment – 7,000
Sunday Expenses – 4,500
Electricity Charges – 5,000
Opening Cash at Bank – 14,000
Donations – 8,000
Rent Paid – 8,000
Locker Rent Received – 2,000
Salaries – 40,000
Closing Cash in Hand – 5,500
Solution:
Receipts & Payments Account
Question 2.
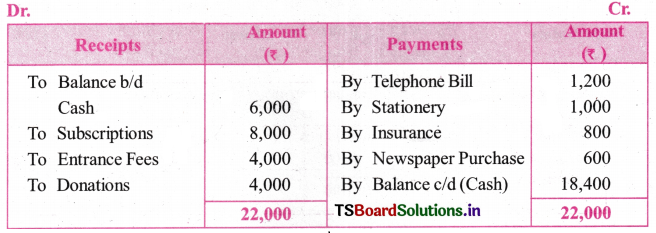
Prepare a Receipt & Payment Account.
Opening cash balance – 6000
Stationery – 1000
Entrance fees – 4000
Newspapers purchase – 600
Telephone bill paid – 1200
Subscriptions – 8000
Insurance paid – 800
Donations – 4000
Solution:
Receipts & Payments Account
Question 3.
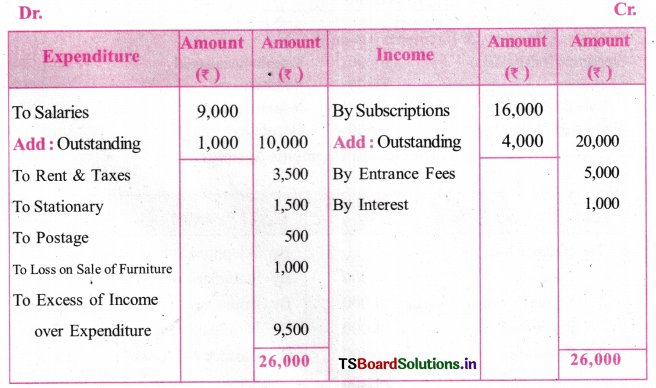
Prepare the Income and Expenditure Account of Leela Chess Academy for the year ended 31st December 2025 from the following particulars.
Receipts & Payments Account
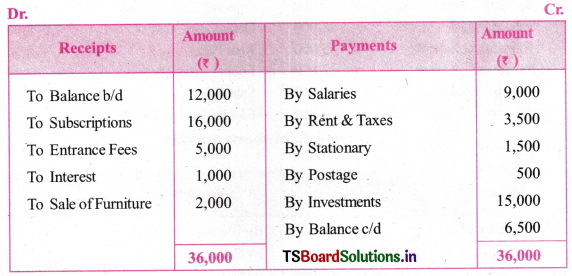
Adjustments:
Salaries outstanding at the end of the year: ₹ 1,000
Subscriptions due for the year 2025: ₹ 4,000.
Book value of furniture sold: ₹ 3,000.
Solution:
In the Books of Leela Chess Academy
Income & Expenditure Account for the year ended 31st December 2025
Question 4.
From the following Receipts & Payments Account of Vaishali Trust, prepare the Income & Expenditure Account for the year ended 31st March 2025.
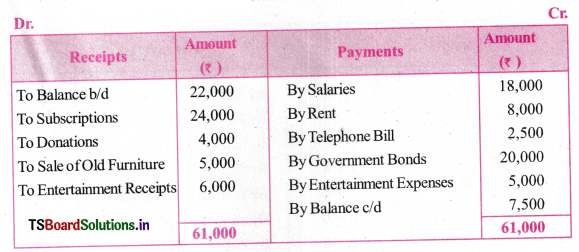
Adjustments:
1. Subscriptions due as on 31.03.2025 were ₹ 6,000;
2. Subscriptions received in advance for 2025-26 were ₹ 1,000.
3. Rent outstanding as on 31.03.2025 was ₹ 2,000.
4. Book value of furniture sold was ₹ 4,000.
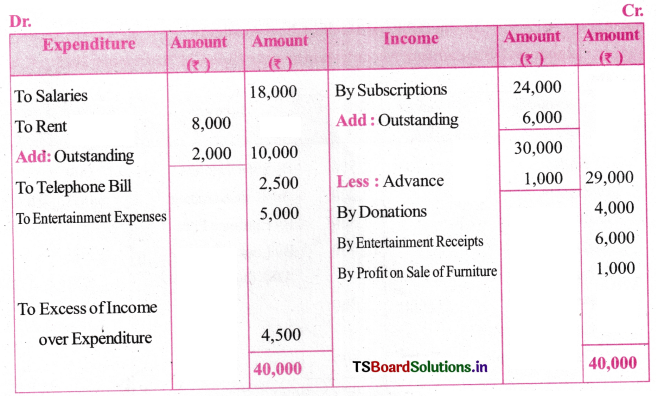
Solution:
In the Books of Vaishali Trust
Income & Expenditure Account for the year ended 31st March 2025
Question 5.
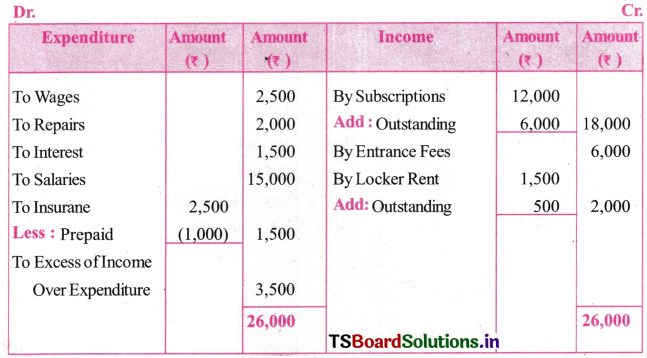
From the following Receipts & Payments Account of Hasini Chess Academy, prepare the Income & Expenditure Account for the year ending 31st December 2025.
Receipts and Payments Account of Hasani Chess Academy
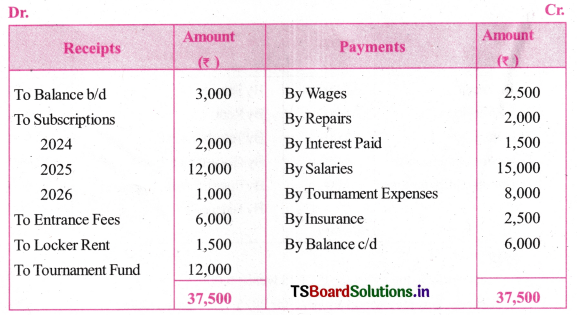
Adjustments:
1. Subscriptions outstanding for the year 2025: ₹ 6,000
2. Prepaid Insurance: ₹ 1,000
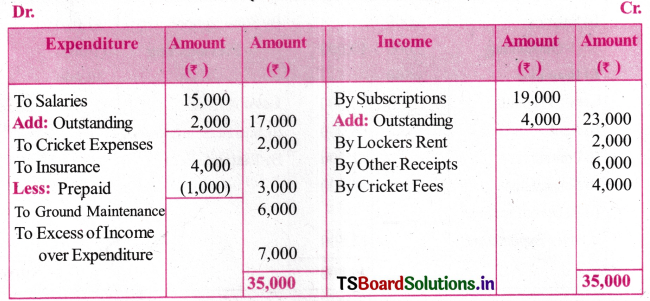
3. Locker Rent due: ₹ 500
Solution:
In the Books of Hasini Chess Academy
Income & Expenditure Account for the year ended 31st December 2025
Question 6.
From the following Receipts and Payments Account of Abhay Cricket Academy, prepare the Income & Expenditure Account for the year ending 31st December 2024.
Receipts and Payments Account of Abhay Cricket Academy
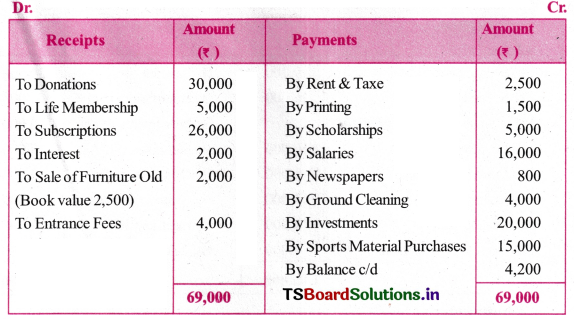
Adjustments:
1. Donations are to be capitalized
2. Subscriptions due as on 31.12.2024: ₹ 5,000.
3. Depreciate Sports Material at 10% per annum.
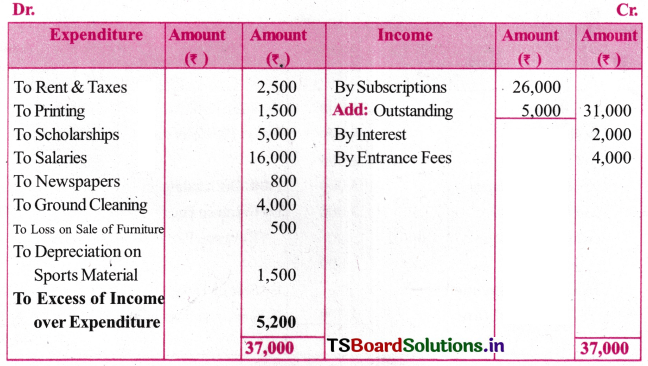
Solution:
In the Books of Abhay Cricket Academy
Income & Expenditure Account for the year ended 31st December 2024
Question 7.
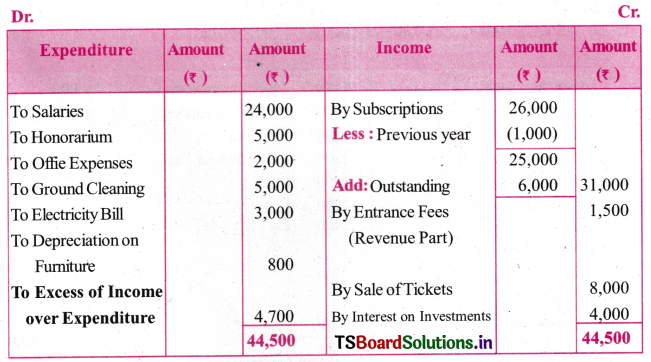
From the following Receipts & Payments Account of Vijayawada Sports Club, prepare the Income & Expenditure Account for the year ended 31st December 2025.
Receipts & Payments Account of Vijayawada Sports Club
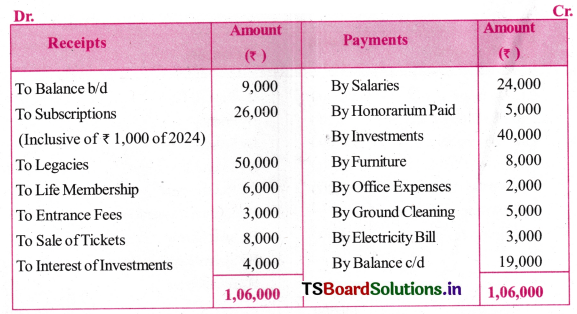
Adjustments:
1. Subscriptions receivable for the year 2025: ₹ 6,000
2. Capitalize 50% of the Entrance Fees
3. Depreciate Furniture at 10%
Solution:
In the Books of Vijayawada Sports Club
Income & Expenditure Account for the year ended 31st December 2025
Question 8.
From the following Receipts & Payments Account of Visakha Charitable Trust, prepare the Income & Expenditure Account for the year ended 31st March 2025.
Receipts & Payments Account of Visakha Charitable Trust
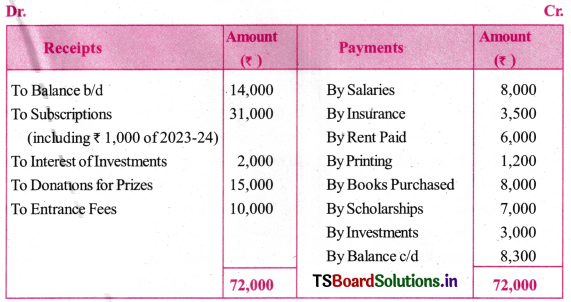
Adjustments:
1. Subscriptions received in advance: ₹ 2,000
2. Prepaid Insurance: ₹ 500
3. Salaries outstanding: ₹ 2,000
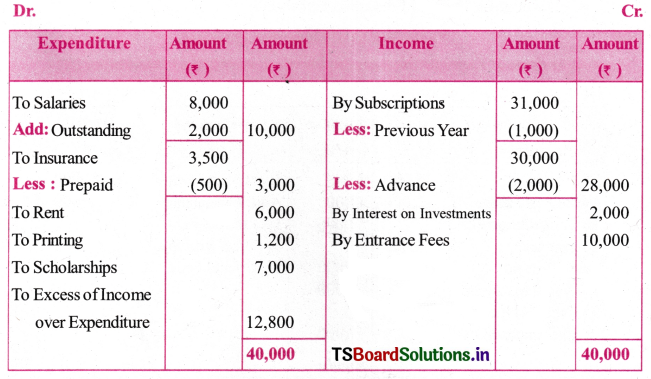
Solution:
In the Books of Visakha Charitable Trust
Income & Expenditure Account for the year ended 31st March 2025
Question 9.
From the following Receipts & Payments Account of Guntur Sports Club, prepare the Income & Expenditure Account for the year ended 31st December 2024.
Receipts & Payments Account of Guntur Sports Club
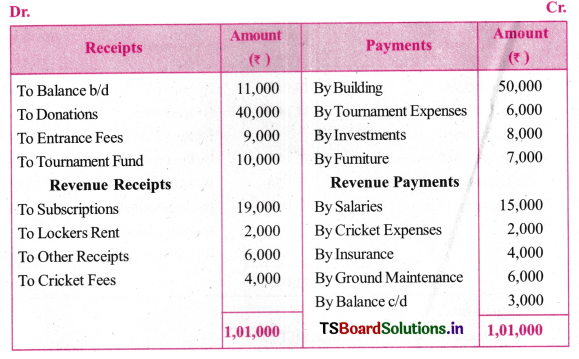
Adjustments:
1. Subscriptions to be received: ₹ 4,000
2. Salaries unpaid: ₹ 2,000
3. Insurance prepaid: ₹ 1,000
4. Donations & Entrance Fees are to be capitalized.
Solution:
In the Books of Guntur Sports Club
Income & Expenditure Account for the year ended 31st December 2024
Question 10.
From the following Receipts & Payments Account of Vizianagaram Cultural Club, prepare the Income & Expenditure Account for the year ended 31st December 2025.
Receipts & Payments Account of Vizianagaram Cultural Club
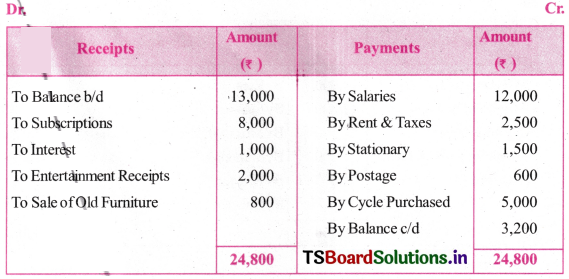
Adjustments:
1. Subscriptions due for the year 2025: ₹ 1,000
2. Book value of Furniture sold: ₹ 1,500
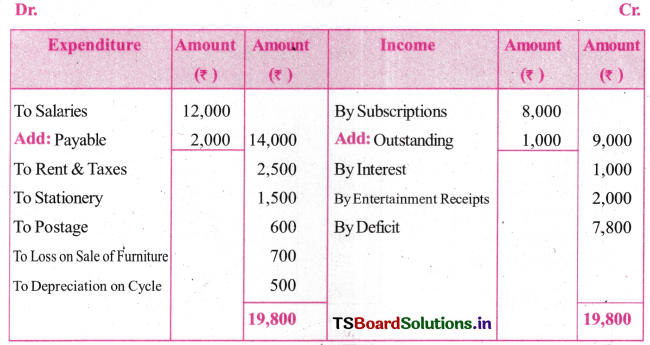
3. Salaries payable as on 31-12-2025: ₹ 2,000
4. Depreciate Cycle at 10%.
Solution:
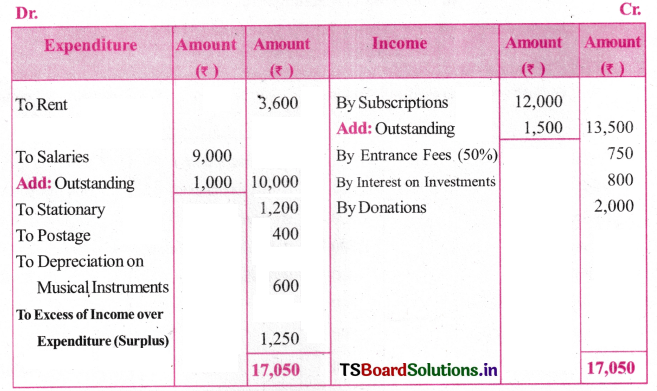
Question 11.
From the following Receipts and Payments Account of Geetansh Cultural Club, prepare the Income and Expenditure Account for the year ended 31st December 2025.
Receipts and Payments Account of Geetansh Cultural Club
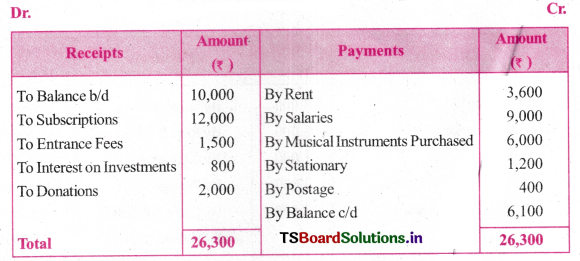
Adjustments:
1. Subscriptions outstanding for 2025: ₹ 1,500
2. Salaries outstanding: ₹ 1,000
3. Depreciate Musical Instruments at 10%.
4. 50% of Entrance Fees is to be treated as capital receipt.
Solution:
In the Books of Geetansh Cultural Club
Income & Expenditure Account for the year ended 31st December 2025
Question 12.
From the following Receipts and Payments Account of Babajee Educational Society, prepare the Income and Expenditure Account for the year ended 31st December 2025.
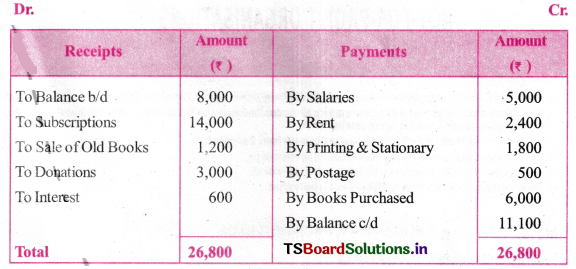
Adjustments:
1. Subscriptions outstanding for 2025: ₹ 2,000
2. Subscriptions 2024: ₹ 1000
3. Rent paid in advance ₹ 400
4. Salaries outstanding as on 31 Dec 2025: ₹ 1,200
Solution:
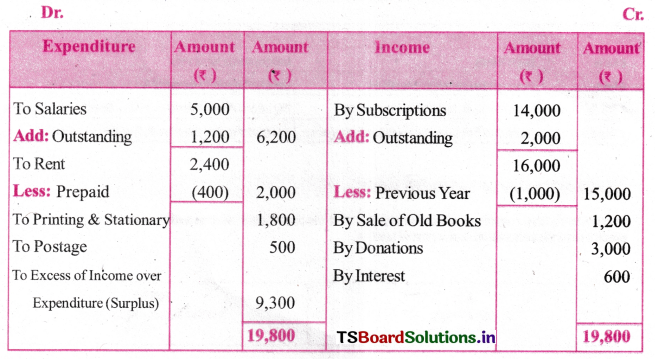
In the Books of Babajee Educational Society
Income & Expenditure Account for the year ended 31st December 2025